

Instacart Shopper Rewards

- 141.00 Reviews
- 4.3
- Downloads
- 100,000+
Our take on Instacart Shopper Rewards from Appgk
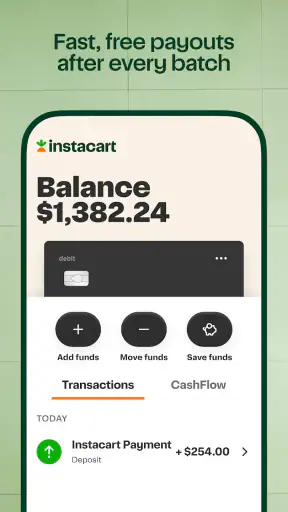
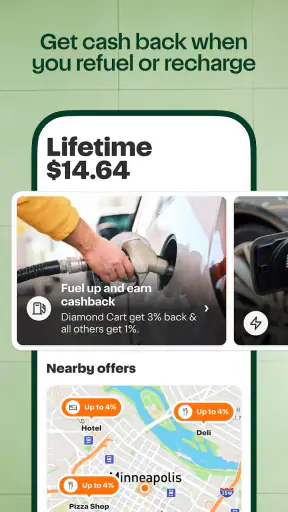
When I first looked at Instacart Shopper Rewards, I approached it less like a general banking app and more like a focused financial tool for people who shop with Instacart. Its store summary points to a new debit card, while the short description identifies it with Instacart Shopper work. That distinction matters: this is not the kind of app I would automatically recommend to every member of a household. I see it as a purpose-built option for a shopper who wants a separate place to handle money connected with that work.
In my experience, the most useful way to judge it is to ask who will actually use the account and who merely needs visibility into household finances. A shopper may want a direct, work-related card, while a partner or parent may only want to help organize spending. Those are different needs, and treating them as the same can create confusion. The app can make sense as one person’s financial workspace, but it should not be treated as a shared family wallet simply because several people live together.
How the app fits a shared household routine
Imagine a realistic weekday: one person in a household accepts shopping work, pays for an ordinary household item later in the day, and wants to keep that activity separate from the account used for rent, subscriptions, and groceries. A dedicated debit-card app can be helpful in that situation because it gives the shopper a clear boundary between personal household money and money associated with the work routine. I would find that separation more useful than trying to make one everyday bank account serve every purpose.
The important point is that the shopper remains the primary user. If another household member needs to understand what is happening, the safest approach is coordination outside the assumption that everyone should sign in. I would discuss who owns the account, who is responsible for the card, and which expenses are personal before installing it on a phone used by several people. That small conversation prevents a common household mistake: confusing access to a device with permission to manage someone else’s financial account.
Best Parts of Instacart Shopper Rewards
Things to Keep in Mind About Instacart Shopper Rewards
A shared phone also changes the practical experience. Notifications, sign-in sessions, and saved account details can become visible to whoever picks up the device. I would avoid leaving the app open on a communal tablet or a phone that children regularly use. Even when a household trusts one another, financial apps deserve a private place because a casual tap can be more serious than opening a shared shopping list.
For a couple, the strongest use case is coordination rather than shared control. One person can use the app for their shopper-related finances, then transfer agreed household amounts through the normal method the couple already trusts. This keeps responsibilities understandable. It also makes it easier to spot whether a purchase belongs to the shopper, the household, or a work task without turning the app into a substitute for a joint budgeting system.
News and Features Related to Instacart Shopper Rewards

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What I would decide before installing it
I would begin by identifying the actual account holder. If I am the shopper, I would use my own device profile and my own sign-in details. If the phone belongs to the household, I would still create a clear private space for the app rather than allowing several people to use the same session. This is not about distrust; it is about keeping financial identity and household convenience from becoming mixed together.
I would also decide whether the debit card is intended for regular personal spending, shopper-related activity, or a mixture of both. Mixing is possible in everyday life, but it makes later review harder. A simple rule such as “use this for shopper money first, and move household money separately” can make the account easier to understand. The app is more useful when its purpose is narrow enough that the balance tells a story.
Don't want to read the full review?
The developer is Branch Messenger, and the app is free to download. That removes an obvious entry barrier, but free access should not be mistaken for a complete household banking solution. I would still read every screen during setup carefully, especially any wording about the debit card, account ownership, and how money is handled. A free app can be convenient while still requiring thoughtful decisions about how it fits into a wider financial routine.
The current version is 2026.8.2, and the minimum operating-system requirement is version 10. That makes the app relevant to people using reasonably current Android devices, but I would check the phone’s software before planning a household rollout. On a shared device, an operating-system update can affect more than one person’s apps, so compatibility is worth checking before the shopper needs the card for a time-sensitive task.
Screenshots
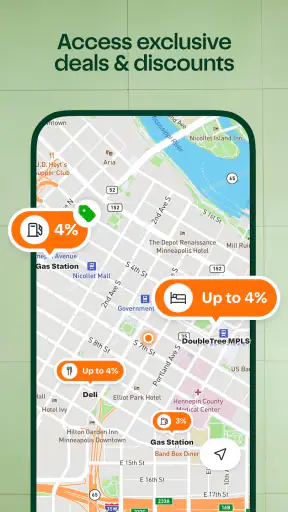
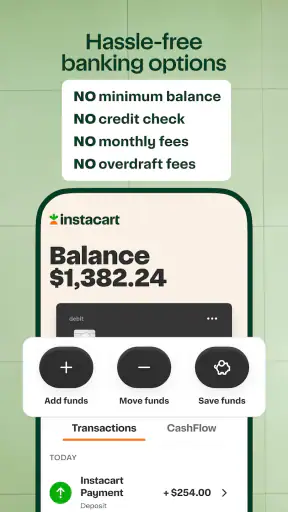
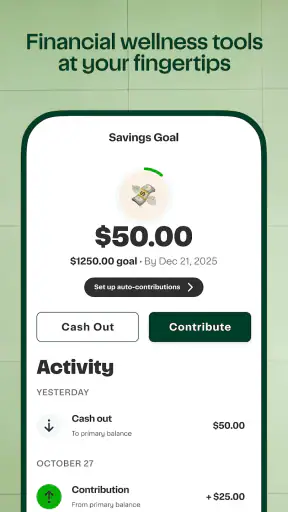
Keeping account boundaries clear
I would not use a single shared login as a shortcut for family coordination. Even if two adults are comfortable sharing money, one account should still have one clearly understood owner. A partner can help with budgeting by reviewing agreed figures or discussing transfers, but that is different from casually passing the phone around with the account open. This boundary is especially important when the app is connected to a debit card rather than being only an information dashboard.
Households with teenagers need an even clearer rule. The content rating is Everyone, but that describes the app’s age suitability, not a promise that a child should manage the account. I would keep the account with the adult or shopper who is responsible for it and explain, in plain language, that a debit card is not the same as a prepaid game balance. A young person might be able to understand the interface while still lacking the judgment needed to make financial decisions.
This is also where trust becomes practical. If a card is left in a shared drawer, everyone should know who may use it and for what. If it stays with the shopper, other household members should know not to borrow it without asking. The app cannot replace those agreements. Its value depends partly on the household respecting the identity behind the account.
I would be cautious about installing the app under a work profile, guest profile, or family member’s phone account without understanding how that device separates personal information. The goal is not to create elaborate technology around a simple card. The goal is to ensure that the shopper can recognize their own session, notices important prompts, and can act without another person accidentally changing the context.
Coordination without turning it into a family wallet
The app can fit neatly into a household budget if everyone agrees on a small number of routines. For example, the shopper might review the balance at the end of a work period, identify which amount belongs to household spending, and then handle that amount through the household’s established process. I prefer this approach to making every family member monitor the app, because it gives the account a clear job and reduces unnecessary exposure of financial details.
A useful habit is to separate “who earned or received the money” from “who eventually spends it.” Those may be different people in one home. If the shopper uses the card for a household purchase, I would record that purchase in the same budgeting method used for other family expenses. If the shopper uses it for personal spending, I would leave it outside the shared budget. This simple classification is more valuable than trying to make the app perform the role of a full family finance planner.
Another practical tip is to agree on a backup plan before the card becomes important. The household should know what to do if the shopper’s phone is unavailable, the card is misplaced, or the app requires attention at an inconvenient moment. I am not suggesting that another person should automatically take over the account. I mean that the family should know who is responsible, where ordinary budget information is kept, and how urgent spending decisions will be handled without guessing.
For roommates, I would be more conservative. A household member is not necessarily a trusted financial partner, and a shared address does not justify shared access. In that setting, I would keep the app and card entirely personal, using ordinary payment methods for shared bills. The shopper can still contribute to rent or utilities, but I would not make the app the central place where roommates coordinate money.
Age, privacy, and trust in everyday use
The Everyone rating makes the app approachable from an age-classification perspective, but I would still treat the financial function as adult responsibility in a household. A child may help hold the phone while a parent checks something, yet that does not mean the child should know a passcode, handle the card, or decide where money goes. I would explain the purpose of the app without giving a young family member unnecessary access.
Older relatives may face a different issue: convenience can encourage them to ask another person to “just keep the app open.” I would avoid that arrangement. If help is needed, I would sit with the account holder, let them remain present, and make sure they understand each action before it happens. Financial assistance should preserve the owner’s awareness rather than quietly transferring control to the most technically confident person in the home.
Trust also includes digital housekeeping. I would sign out when the device is shared, avoid saving details where other users can reach them, and remove the app from a phone before handing that phone to someone else. These are ordinary precautions, but they matter more here because the app is tied to a debit card. A household that already has separate user profiles and sensible device habits will find this easier than a household where everyone uses one unlocked phone.
I also would not judge the app solely by its rating. It has an average rating of 4.3 from around 550 ratings, which suggests that many users find it worthwhile, but a rating cannot tell me whether it suits my household’s boundaries. A shopper who needs a work-focused card may be satisfied, while a person searching for joint budgeting, family allowances, or broad banking tools may reasonably prefer another type of financial app.
Where it beats ordinary alternatives—and where it does not
Compared with keeping all money in a traditional bank account, the main appeal here is focus. A shopper can give work-related finances their own place instead of mixing them with rent, savings, and everyday household transactions. That can make mental accounting easier, particularly for someone whose income and spending patterns already revolve around Instacart Shopper activity.
Compared with a general budgeting app, this is a more direct financial tool because the debit-card idea sits at the center of the experience. A budgeting app may be better for seeing several bank accounts, setting household categories, or planning long-term goals. I would choose the budgeting app when the family needs a broad overview. I would choose this one when the shopper wants a dedicated, simpler route for the relevant card and account routine.
Compared with a joint bank account, the boundaries are clearer when only one shopper owns the account. That can be a strength for couples who want to cooperate without merging every financial activity. It is also a limitation: if both partners need equal authority over shared money, a properly structured joint account is likely to be more appropriate than trying to imitate one through informal access.
The app is also not automatically the best choice for someone who does not shop with Instacart. Its short description is specifically “Instacart Shopper,” so I would not install it merely because I wanted a free debit card. The connection to shopper use is central to the reason I would consider it. Someone looking for an all-purpose everyday bank, investing platform, or family allowance system should start elsewhere.
Small workflow choices that make a difference
My first useful tip would be to give the account a defined review moment. Instead of checking it randomly whenever a notification appears, I would look at it during a weekly household money check and decide what portion belongs to personal spending, shopper-related costs, or shared expenses. This turns the app from a passive card companion into one step in a repeatable routine.
My second tip is to avoid using the card as a vague “miscellaneous” fund. If every unclassified purchase goes through it, the separation benefit disappears. I would keep a short note beside the household budget showing the purpose of the account and the rule for moving money out of it. That is especially useful when two adults coordinate finances but only one person uses the app.
My third tip concerns shared devices: use the app only in the shopper’s private device space, even if the phone is technically available to everyone. This reduces accidental switching between accounts and makes it easier to notice when the app needs attention. It also creates a healthy expectation for children, guests, and roommates that financial apps are not communal entertainment.
A fourth trade-off is convenience versus separation. Paying for everything from one card may feel simple, but later it can be difficult to explain which purchases were household expenses and which were personal. Keeping the card’s purpose narrow takes a little more planning at the start, yet it gives the account a clearer role. I think that trade-off is worthwhile for organized shoppers and less worthwhile for someone who dislikes tracking categories.
My household verdict
After considering the app as a finance tool rather than simply a card download, I see a sensible niche for it. Its strongest role is a private shopper-focused account that can coexist with a household budget, not replace one. I would recommend it to an Instacart shopper who wants clearer separation, understands that the account belongs to one user, and is willing to establish a simple routine for personal and shared spending.
I would be more hesitant to recommend it to a family looking for one shared financial hub. The Everyone rating may make it easy to find, and the free price makes trying it less intimidating, but neither point changes the need for adult ownership and careful device boundaries. Families should coordinate around the account without assuming that every person needs direct access to it.
The app’s 100K-plus installs show that it has reached a meaningful audience, while its 141 reviews provide additional user feedback beyond the headline rating. I would treat that visibility as a reason to investigate, not as proof that it will suit every household. The right question is whether its shopper-centered purpose matches the way money is actually organized at home.
For me, the final decision comes down to clarity. If the shopper can say why the account exists, who controls it, how the card will be used, and how household contributions will be recorded, this app can be a practical addition. If several people need equal access, if the household wants detailed joint budgeting, or if the user is not connected with shopper work, a conventional bank or broader budgeting option will probably be a better fit. I would install Instacart Shopper Rewards for the focused use case, keep it private to the responsible shopper, and make the household agreement around it before relying on the card.
Instacart Shopper Rewards FAQ
What is Instacart Shopper Rewards?
Instacart Shopper Rewards is a benefits program designed for eligible Instacart shoppers. It may provide access to rewards, discounts, savings, or other perks connected with shopping and delivering orders. The exact benefits can vary by location, shopper status, and current promotional terms, so it is important to review the details shown in the app before relying on a particular reward or offer.
Who can use Instacart Shopper Rewards?
Availability generally depends on whether you are an active Instacart shopper and whether the program operates in your area. Some features may require completing specific deliveries, meeting eligibility requirements, or maintaining an account in good standing. New and existing shoppers should check the eligibility information inside the official Instacart app or program page because requirements can change over time.
Does Instacart Shopper Rewards cost anything?
The rewards program itself may be available at no additional charge to eligible shoppers, but individual offers can include conditions, exclusions, expiration dates, or minimum requirements. A reward is not necessarily the same as cash payment, and some benefits may be provided through partner services. Always read the terms before activating an offer, especially when a purchase, subscription, or payment method is required.
How do I redeem rewards in Instacart Shopper Rewards?
Redemption instructions depend on the specific reward. After signing in, look for available offers, eligibility details, expiration dates, and any activation button or code. Some rewards may be applied automatically, while others require selecting a partner benefit or completing an additional step. If an offer does not appear, confirm that your account qualifies and that the app is updated.
Is Instacart Shopper Rewards safe to download and use?
The safest approach is to access Instacart Shopper Rewards through the official Instacart Shopper app, official website, or a trusted app store rather than downloading unofficial files or modified versions. Protect your login information, review requested permissions, and avoid links asking for sensitive details outside official channels. Rewards, availability, and terms may change, so verify current information before participating.












